Share


When higher education institutions need to reduce costs, labor is often the first place leaders look.
And for good reason. Labor typically represents 60–70% of operating expenses at research universities. But knowing where to reduce higher education labor costs without compromising essential capacity is much harder than simply identifying the largest budget lines.
The challenge isn't necessarily finding areas where spending is high. It's understanding whether that spending is appropriate—and how it compares with similar institutions and aligns with your goals.
That's where HelioCampus Labor Cost Analytics can provide a different perspective for your institution.
Why Should Higher Ed Leaders Look Beyond Headcount to Understand Labor Costs?
Most institutions understand their labor costs through organizational charts and budget categories: which department employs someone and which budget line funds their position.
That view tells you what you're spending. But it doesn't necessarily tell you what work is being performed, where that work is happening, or whether the investment is in line with peer institutions.
An activity-based approach provides a more complete picture. But taking an activity-based approach requires standardization across job activities occurring on campus, which is where most institutions fall short. They lack enough data, or get weighed down deciding how to map activities at the appropriate level for trend analysis and decision-making. We've solved this with HelioCampus Labor Cost Analytics by mapping $375 billion dollars across our client consortium into our Standard Activity Model (SAM), which makes it possible for institutions to reliably compare how they allocate labor even when their organizational structures are very different.
That distinction can uncover costs that aren't obvious from the budget alone.
For example, Finance-related work may be performed across dozens of departments—not just within the central Finance office. An activity-based view can reveal the difference between what the organizational budget says a function costs and what the institution is actually spending on that work.
What happens when your staffing costs are out of line with benchmarks?
One large public research university turned to activity-based benchmarking while navigating multimillion-dollar administrative cost reductions across two consecutive budget cycles.
Rather than starting with across-the-board cuts, leadership established an external benchmark using more than 20 flagship public research universities. Each institution was mapped using the same activity framework, creating a consistent basis for comparison.
The analysis surfaced a significant finding: Research Compliance was running above peer norms.
That didn't automatically mean the institution needed to cut Research Compliance staffing. Instead, it identified an area where leadership needed to ask better questions.
-
Did the institution's research scale justify the higher investment?
-
Was the function organized differently?
-
Was there an opportunity to restructure the work?
Those questions led to a deeper analysis of Research Compliance, including a comparison of centralized and distributed models across 22 peer institutions and an examination of the function at the school and college level.
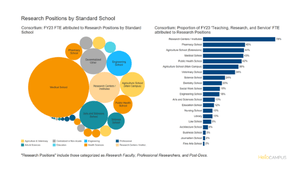
Research Positions by Division from HelioCampus Labor Cost Consortium
How Can Data-Driven Benchmarks Protect Labor Cost Decisions from Internal Pushback?
Benchmarks can’t make the decision for leadership, but they can make the decision more defensible.
With an external, peer-grounded view of its Research Compliance investment, the institution could move beyond internal budget data and evaluate its organizational structure in context.
For leaders facing scrutiny from faculty governance, boards, or system leadership, that distinction matters. When difficult decisions have to be made, internal spending data alone may not provide enough context to explain why one area should change while another should remain protected.
A stronger approach is to understand:
- What work is being performed?
- Where is that work happening?
- How much labor is supporting it?
- How does that investment compare with peers?
- Are differences driven by institutional needs or organizational structure?
The answers can help leaders move from broad cost targets to more targeted conversations about staffing and organizational efficiency.

When Should Higher Ed Leaders Establish Labor Cost Baselines?
Labor cost analytics can also support longer-term planning—not just immediate cost reduction. While many institutions evaluate staffing because of a budget fire drill, long-term benefits for organizational planning await many institutions on the other side.
In this case, the institution established an activity-mapped baseline before transitioning to a new enterprise resource planning (ERP) system. That baseline gives leadership a way to measure whether anticipated efficiency gains actually occur after implementation.
Without a clear baseline, it can be difficult to determine what changed after a major transformation—or whether the promised efficiencies materialized.
With one, leaders can measure the difference between where they started and where they end up.
What Is Required to Maintain Activity-Based Labor Analytics Over Time?
Higher education labor costs and organizational structures don't stand still. That's why a one-time analysis may not be enough.
Institutions that want to take an activity-based approach need to establish requirements for tracking changes, incorporating evolving peer data, and revisiting specific functions over time, which is where HelioCampus' established consortium, annually refreshed data, and standard activity model come in handy.
For example, an institution can establish a baseline today, make organizational changes, and return to the benchmark later to evaluate whether those changes produced the intended results.
The goal isn't simply to understand where your institution stands today. It's to build the intelligence needed to understand where it's headed.
Make Higher Education Labor Costs More Strategic
Reducing higher education labor costs doesn't have to mean applying the same percentage cut across every department.
A more targeted approach starts with understanding what work is being performed, where it's being performed, what it costs, and how that investment compares with peers.
Activity-based labor benchmarking gives higher education leaders the evidence they need to have more productive conversations about staffing, organizational structure, centralization, and efficiency.
Because when the decisions are difficult, having the data to explain—and defend—them matters.
See Where Your Labor Costs Stand
HelioCampus Labor Cost Analytics helps institutions benchmark administrative labor, understand how work is distributed across the organization, and identify opportunities for more strategic cost management.
